What informs our decision, what changed since we last looked, and why did we decide that

Aster Biologics is piloting an electronic batch-record system on one production line. Before it goes live, a consultant and the client's compliance lead must say which requirements of 21 CFR Part 11 apply to this workflow, and whether the client's own procedures meet them. Five requirements are in scope. Aster, its people, and its documents are fictional. The regulation and the FDA guidance are real.

1. What informs our decision?

Bring text, numbers, calculations, and relationships together into one managed basis for judgment.

An assessment references a combination of inputs. For Aster, the combination is the clause in 21 CFR 11.10(k), the consultant’s reading of what that clause asks of this client, the paragraph in the client’s own procedure that answers it, and the compliance lead’s reasons for calling that sufficient.
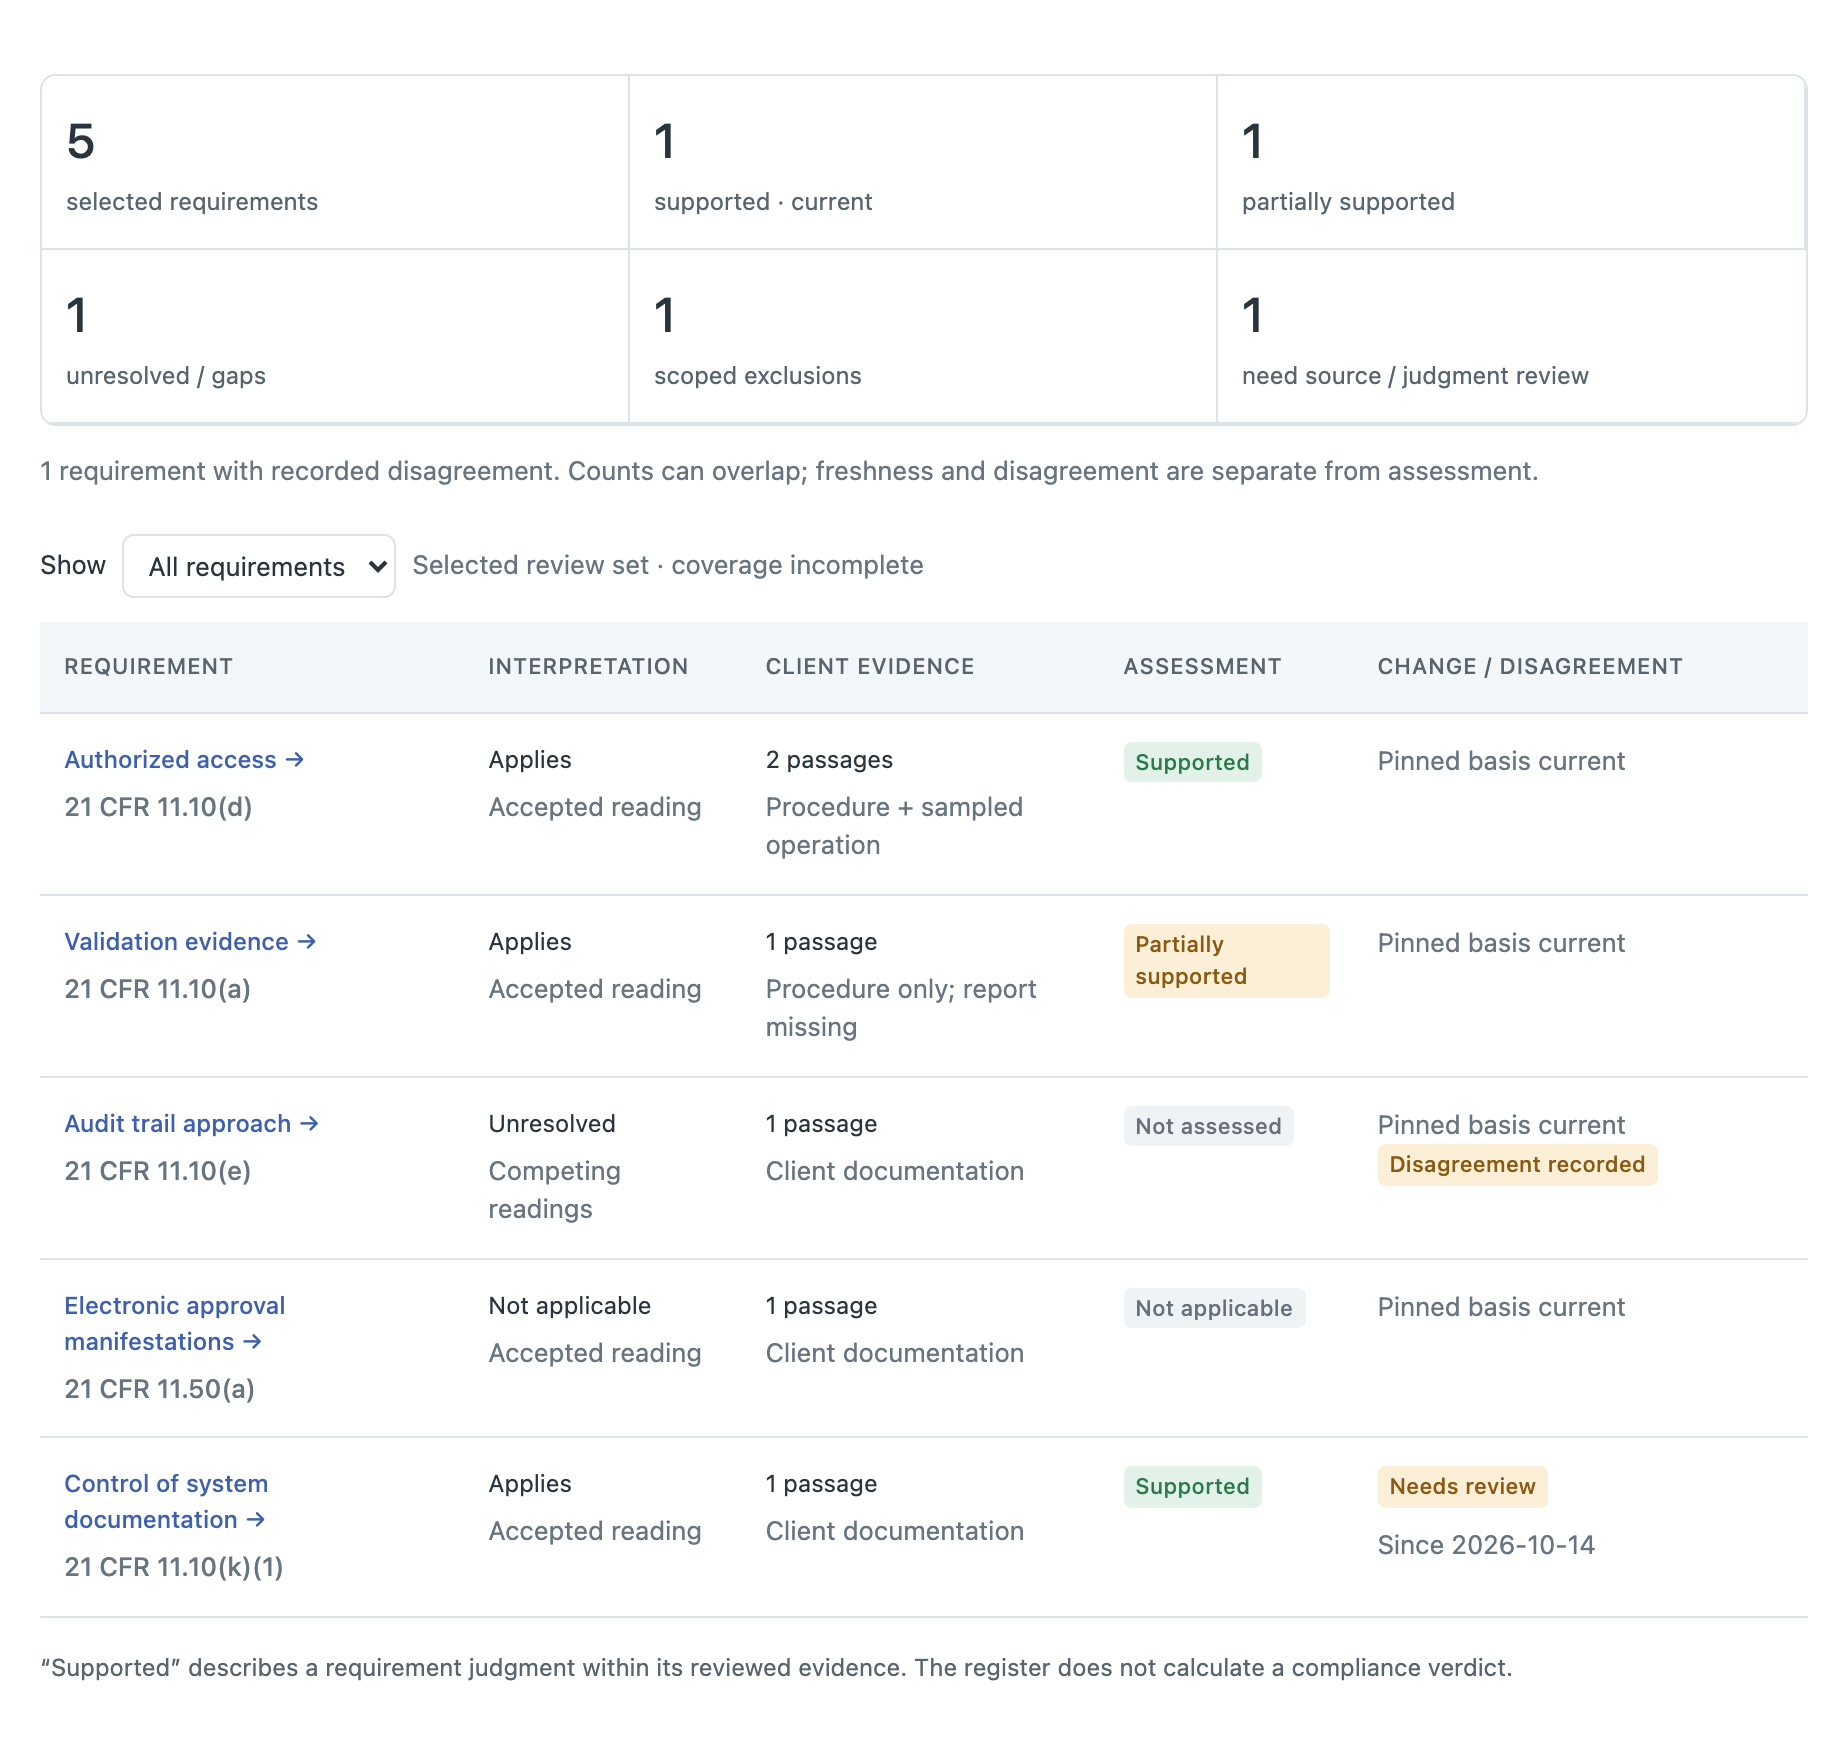
The requirements register in the Exeges inquiry prototype: five requirements of 21 CFR Part 11, each with its interpretation, client evidence, assessment and change status. Counts above read five selected, one supported, one partially supported, one unresolved, one scoped exclusion, one needing review. One row carries a recorded disagreement; one reads Needs review since 2026-10-14. A footnote says the register does not calculate a compliance verdict.
The requirements register for Aster's pilot, in the Exeges inquiry prototype. Five requirements, each with its interpretation, client evidence, and assessment, and the register's own footnote: “supported” describes a judgment within its reviewed evidence. It does not calculate a compliance verdict. View full screenshot ↗

2. What changed since we last looked?

Each new version is rendered into a change map; an agent is dispatched to investigate the change.

Because references are anchored to source material, change arrives already joined to the record.

Regulations and guidance · financial filings and debt agreements · contracts · your own procedures and policies.

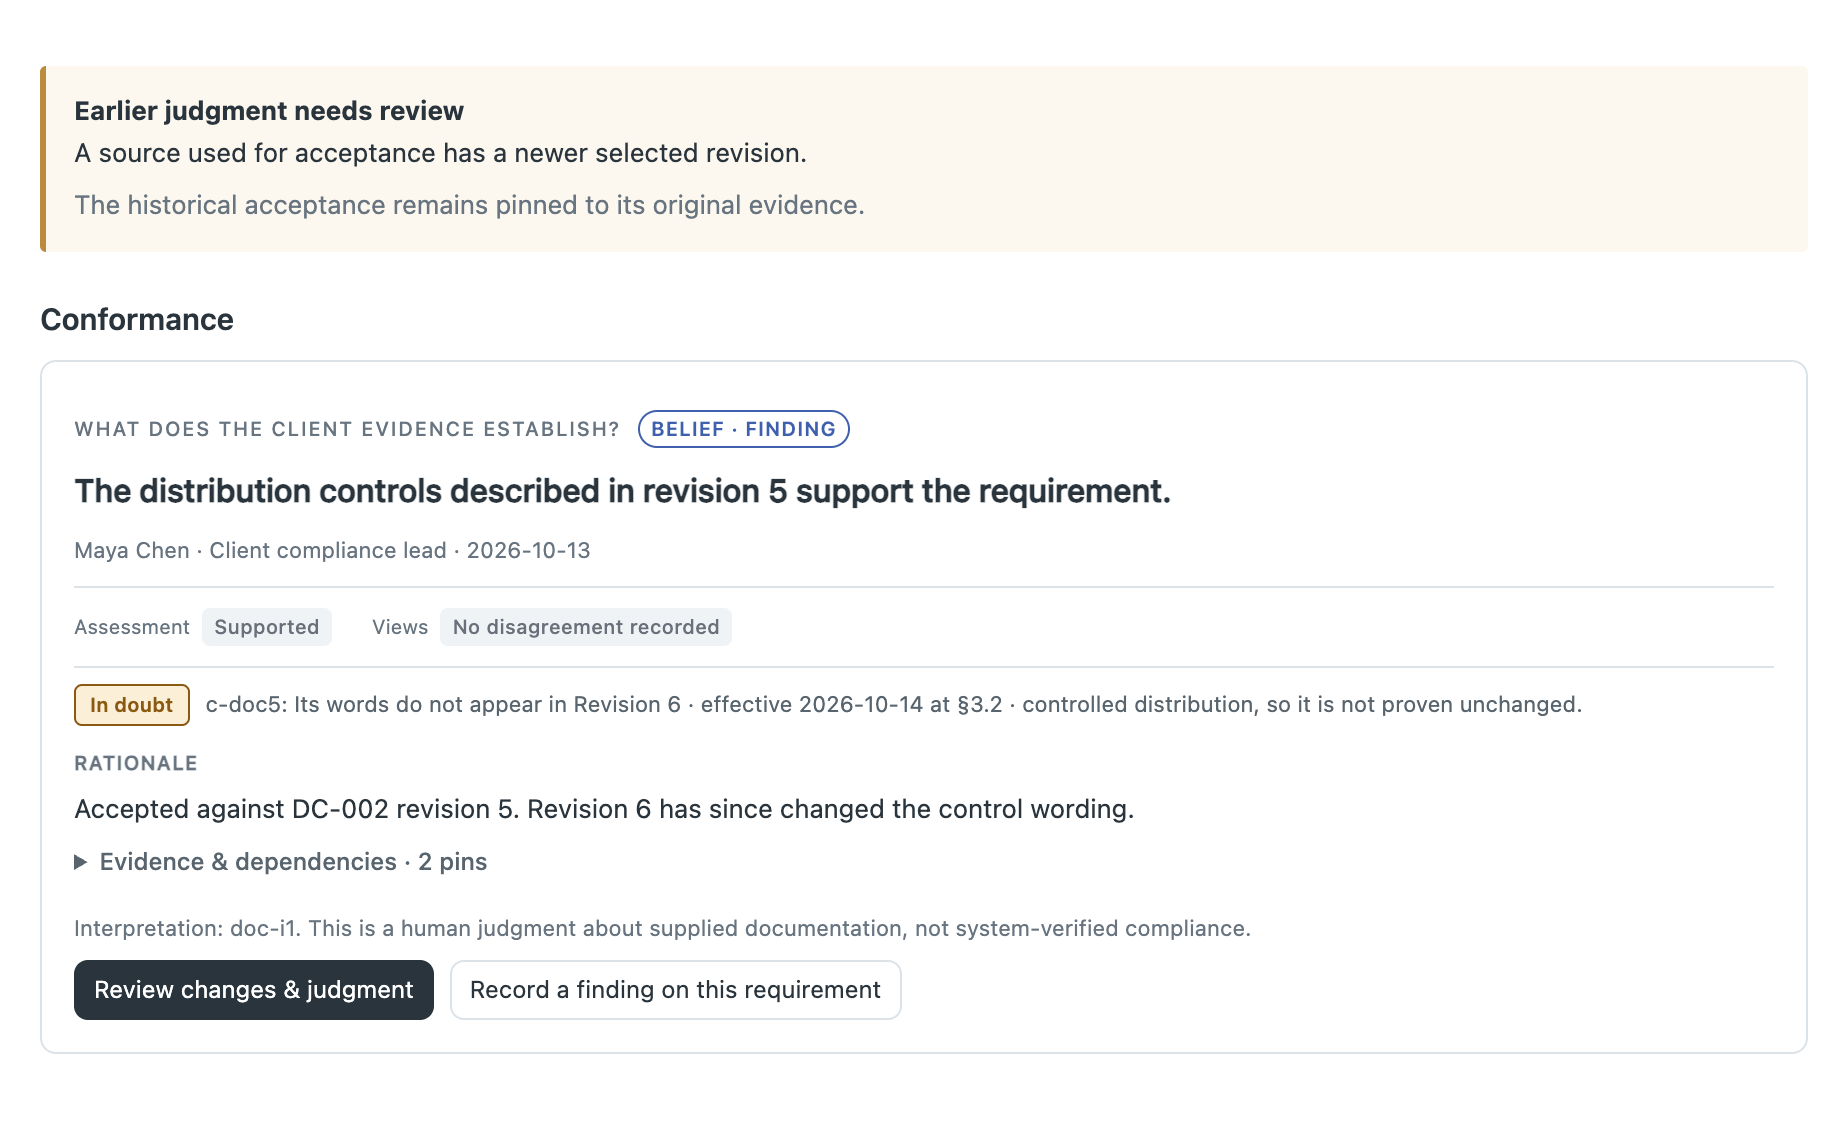
A judgment card in the Exeges inquiry prototype under a notice reading Earlier judgment needs review: a source used for acceptance has a newer selected revision; the historical acceptance remains pinned to its original evidence. The card reads: the distribution controls described in revision 5 support the requirement, Maya Chen, client compliance lead, 2026-10-13, assessment supported, and is badged In doubt because its words do not appear in revision 6, effective 2026-10-14.
The judgment on Aster's document-control requirement after revision 6 of the procedure arrived. Accepted against revision 5 on 13 October; in doubt since 14 October because the passage it rested on does not appear in the new revision. Nothing has been moved. View full screenshot ↗

3. Why did we decide that?

Every position your team ever took, still answerable years later: who held it, what it rested on, and who disagreed.

An assessment replays exactly as it was recorded: the conclusion, the version of the passage it cited, who made the call, and when.

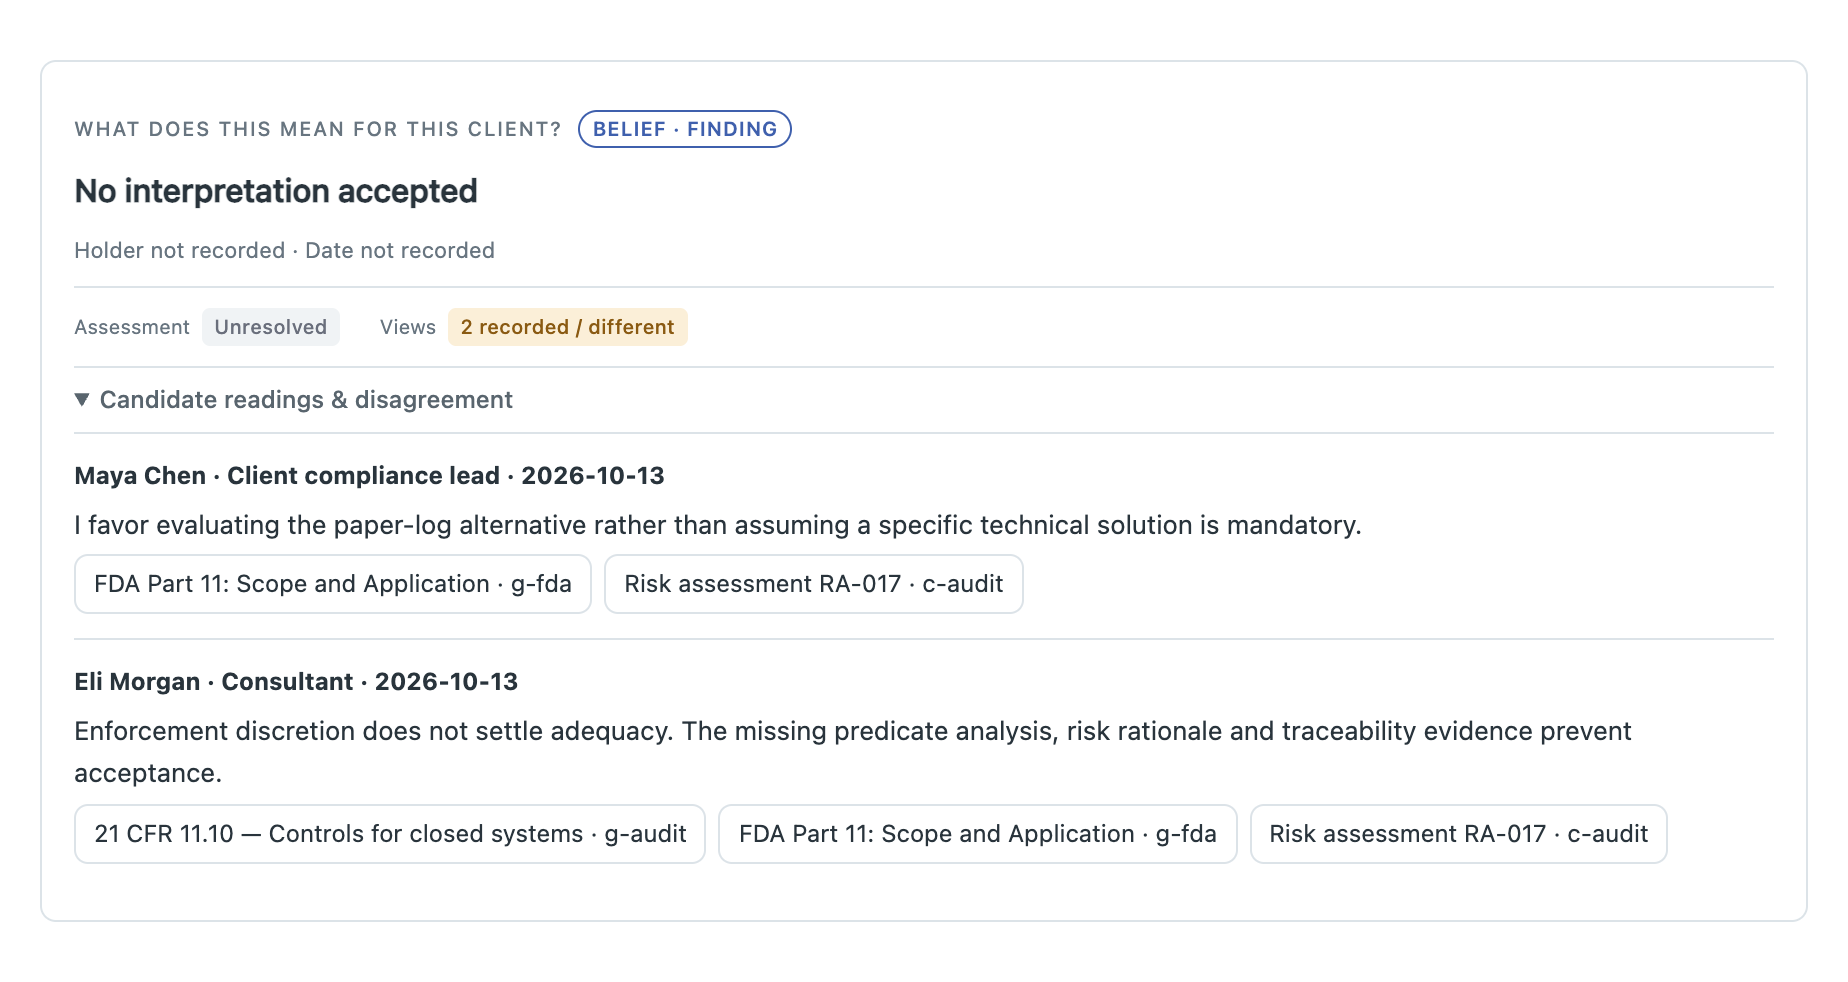
An interpretation card in the Exeges inquiry prototype reading No interpretation accepted, holder not recorded, assessment unresolved, views: two recorded, different. Under Candidate readings and disagreement, two statements: Maya Chen, client compliance lead, 2026-10-13, favours evaluating the paper-log alternative, citing the FDA Part 11 guidance and risk assessment RA-017; Eli Morgan, consultant, 2026-10-13, says enforcement discretion does not settle adequacy, citing 21 CFR 11.10, the guidance and the same risk assessment.
Two readings of one requirement, recorded on 13 October by the client's compliance lead and the consultant, each with its reasons and the passages it rests on. The requirement stays unresolved until someone accepts a reading, and both readings stay on the record after that. View full screenshot ↗

The same three questions, other material

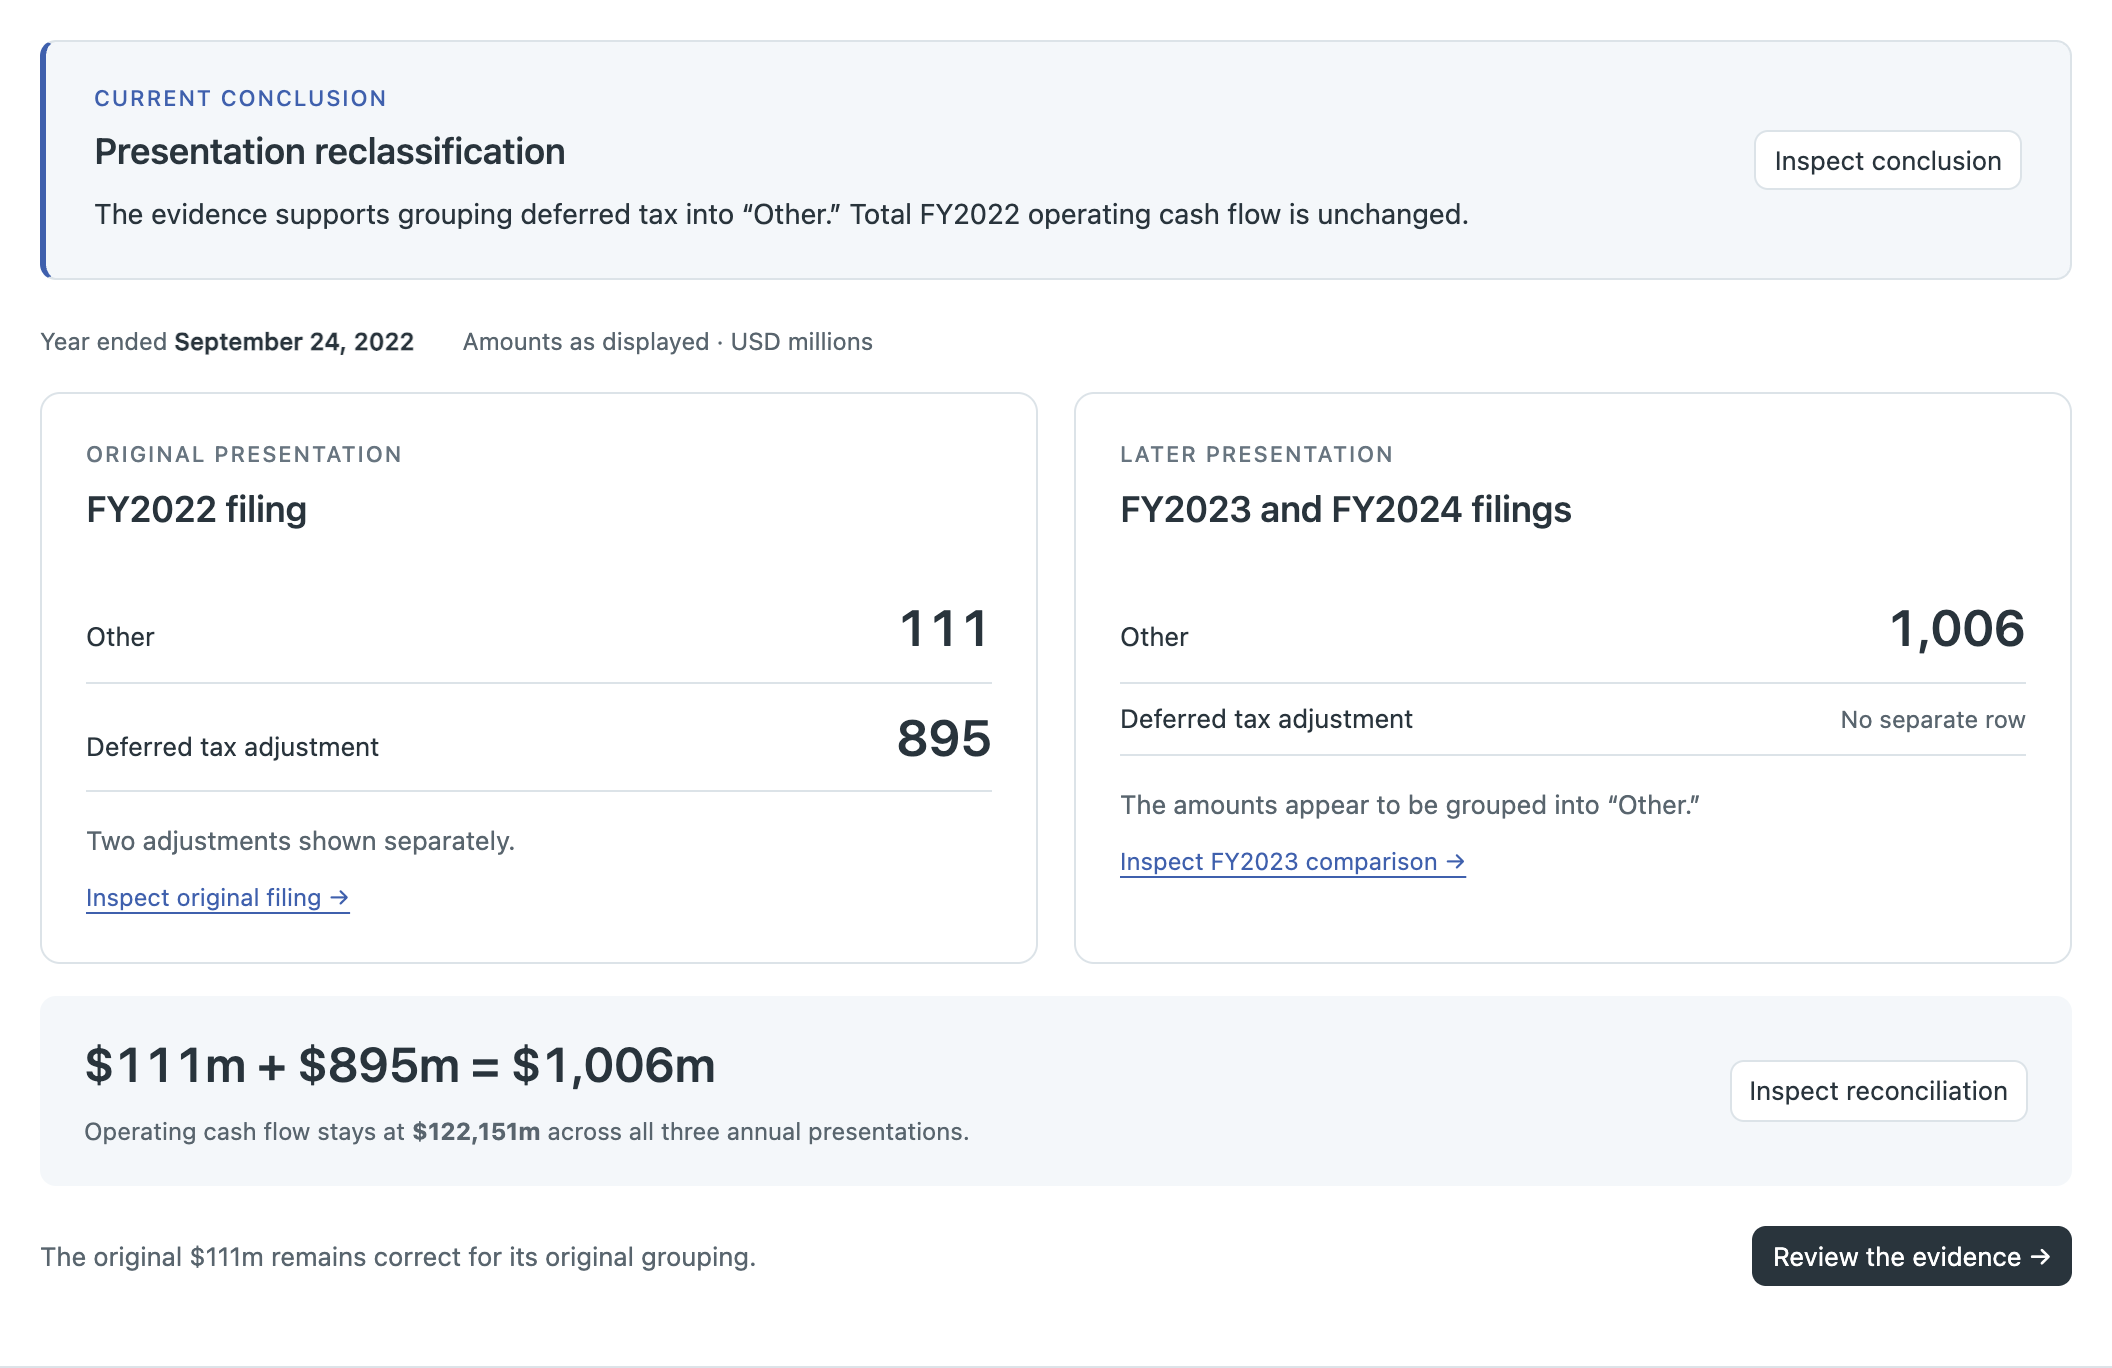
  1. What was Apple's FY2022 “Other” non-cash adjustment?

    Three annual SEC filings, FY2022 to FY2024. Real.

    $111m in the FY2022 filing · $1,006m for the same year in the two later filings · a presentation reclassification, with the original figure kept as correct for its original grouping

    PrototypeView screenshot ↗
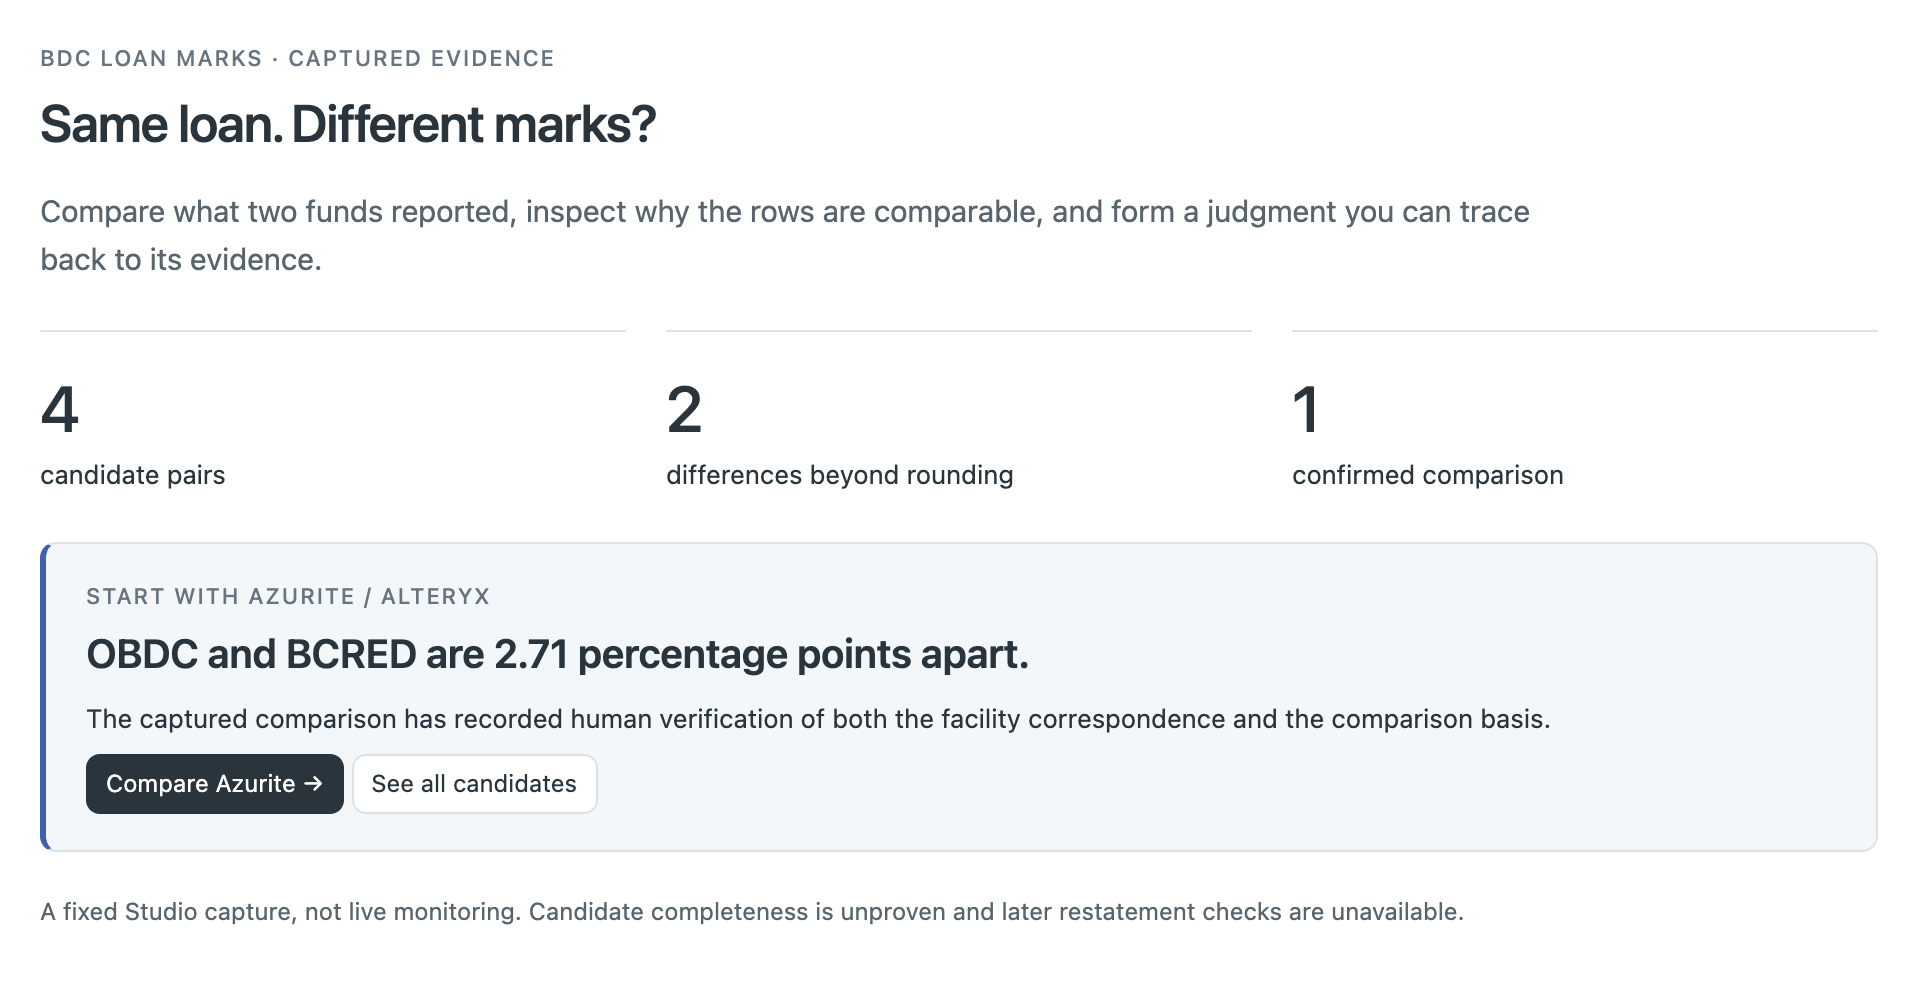
  2. Is this loan marked differently across funds?

    Public filings of two business-development companies. Real.

    4 candidate pairs · 2 differences beyond rounding · 1 confirmed comparison · completeness unproven

    PrototypeView screenshot ↗
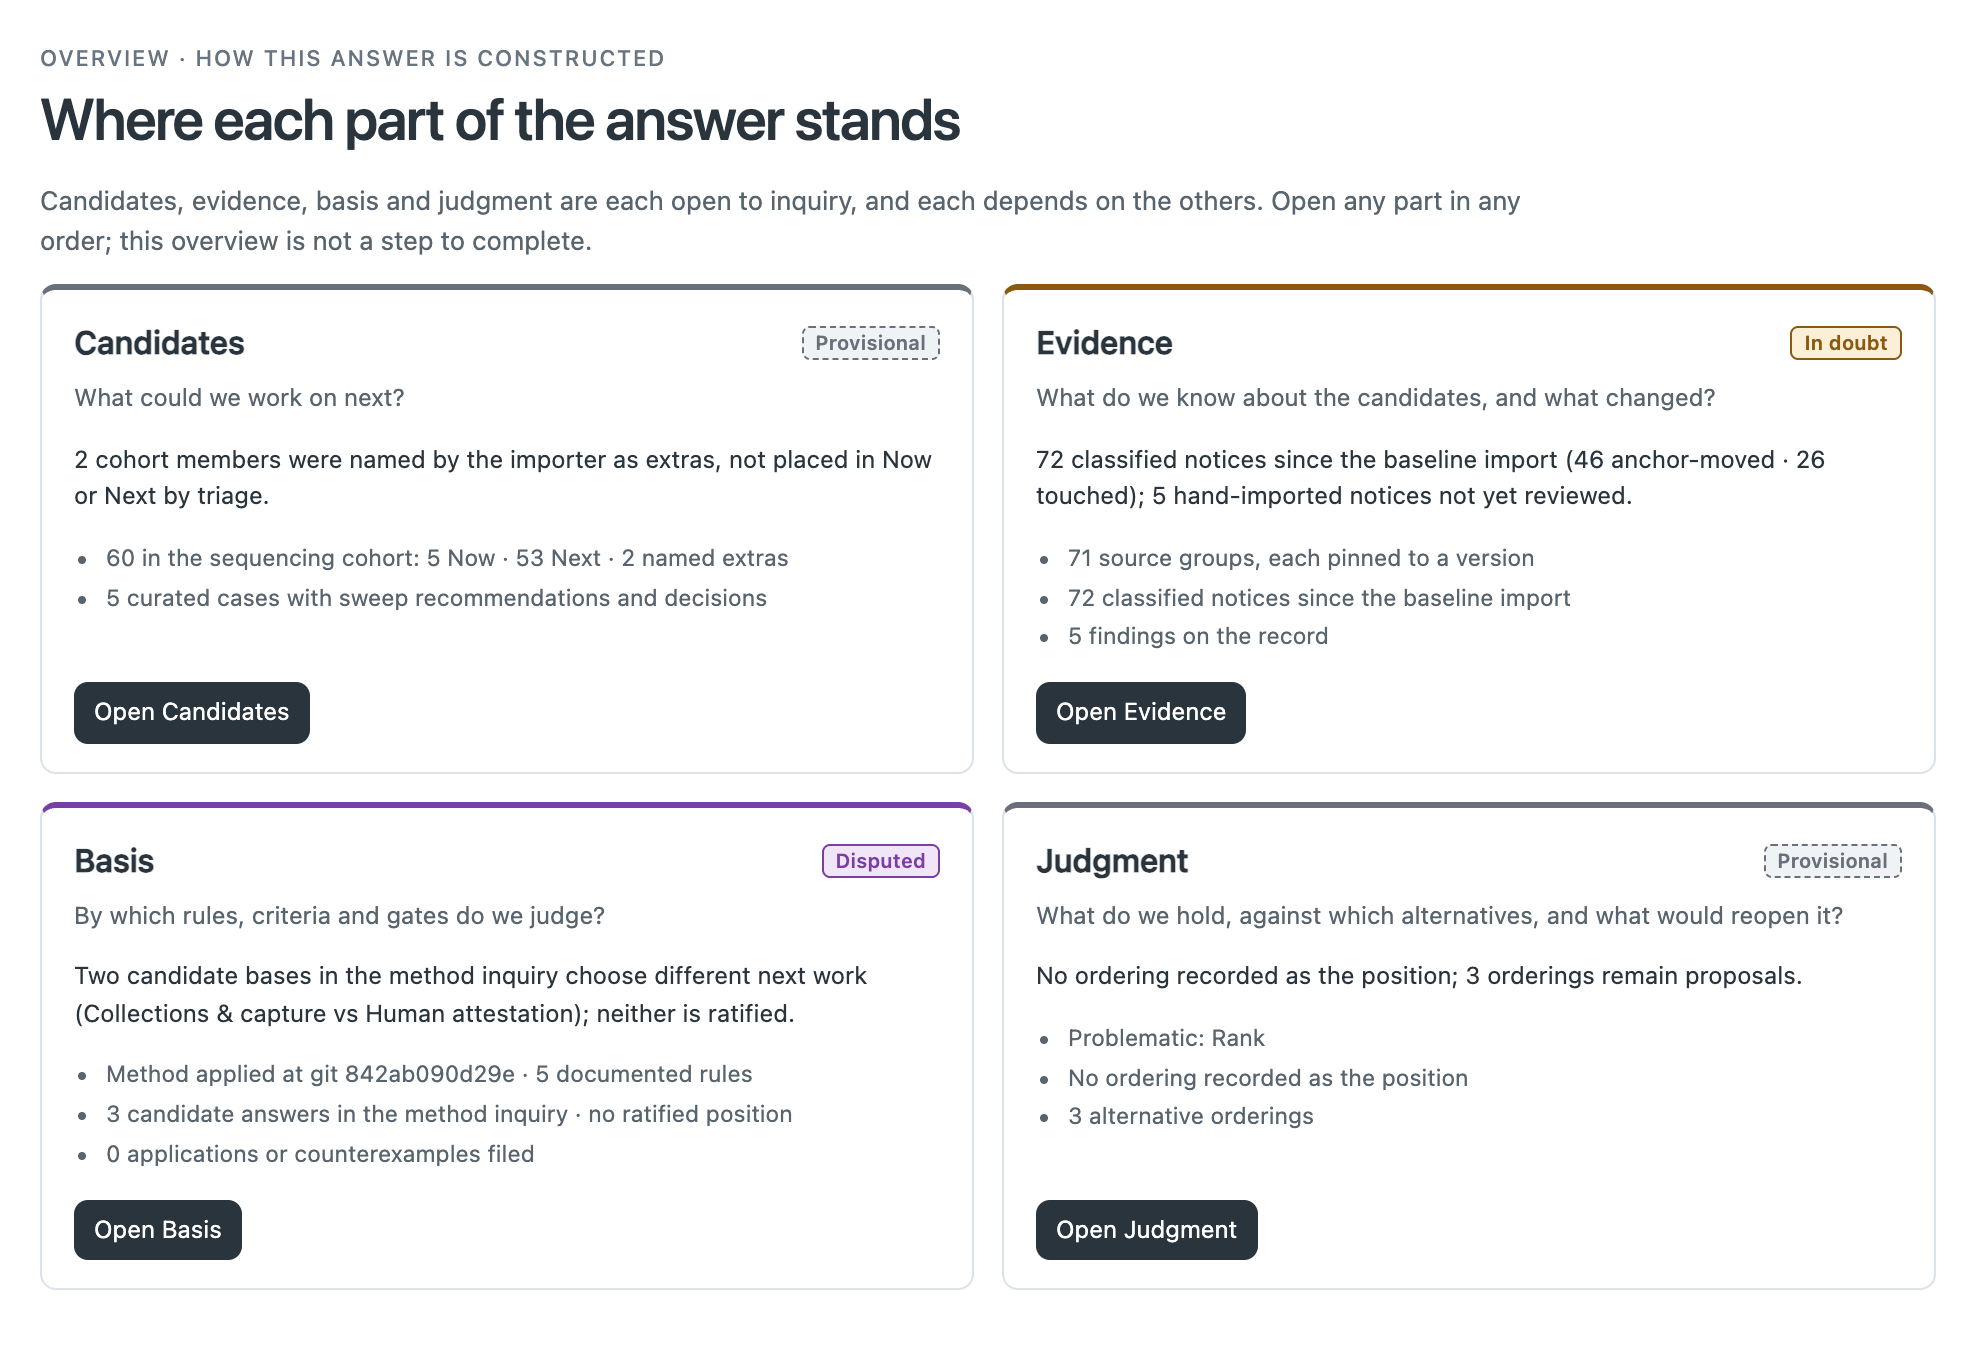
  3. What should we work on next?

    A team's own project plans and backlog. Internal.

    Evidence in doubt since the last import · basis disputed between two candidate methods · no ordering recorded as the position · 3 alternative orderings

    PrototypeView screenshot ↗
  4. What do the records say, and where do the accounts differ?

    A family's appointment records and their own diary. Synthetic.

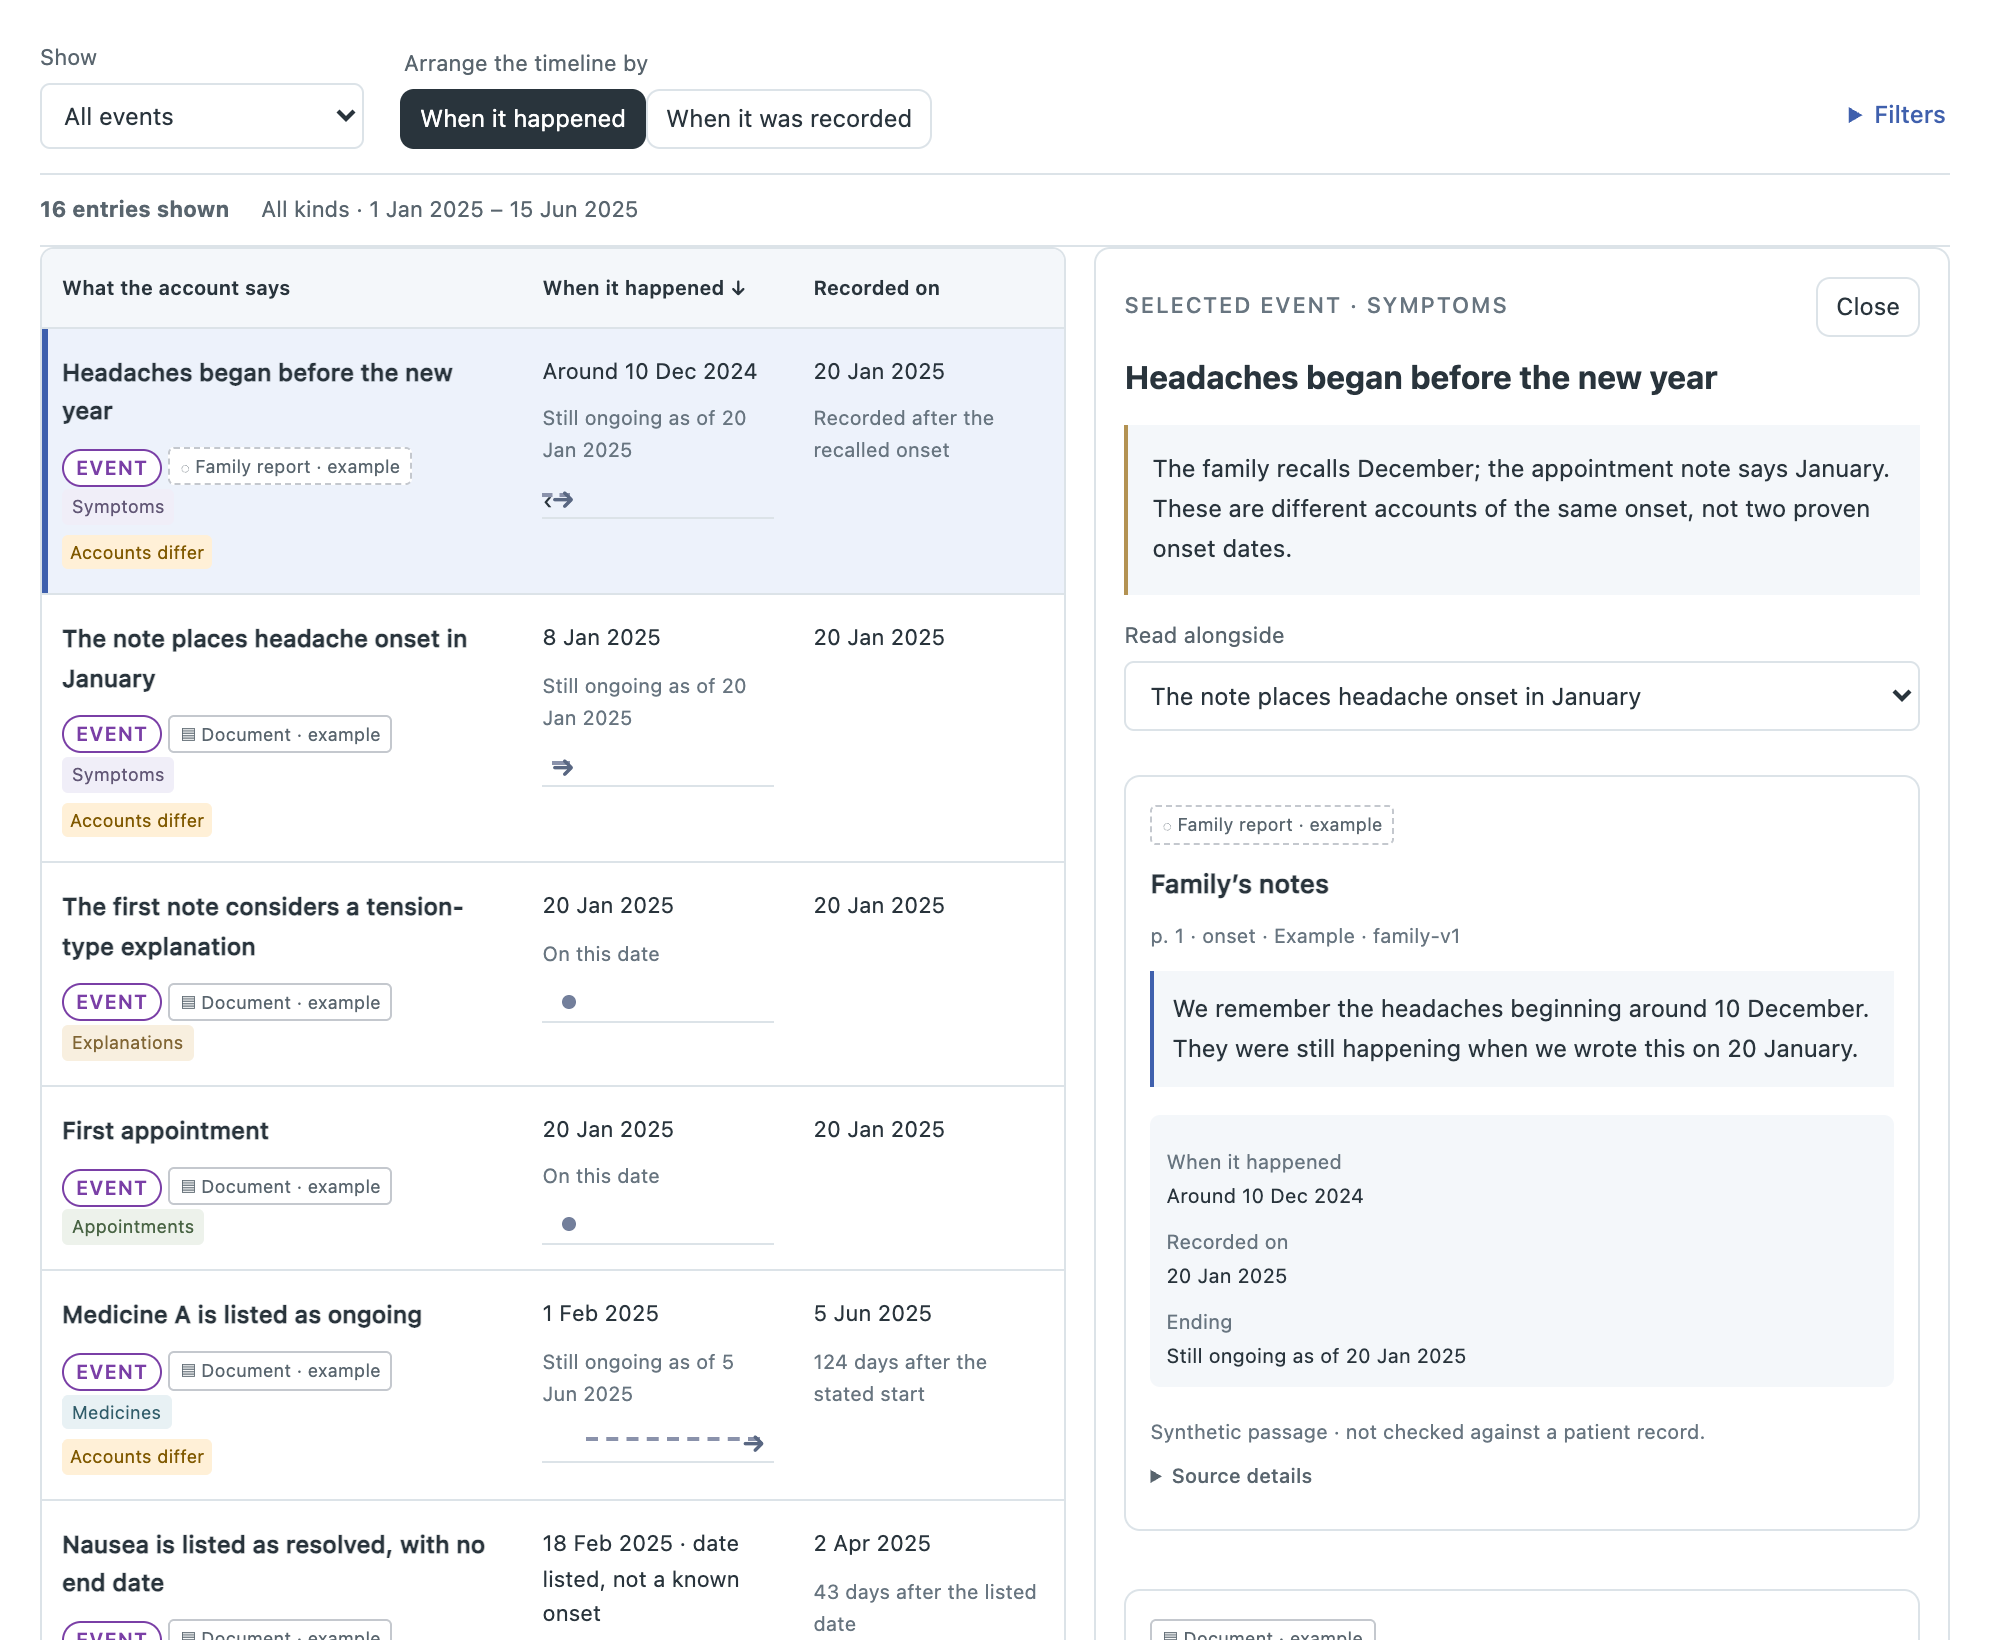
    16 dated accounts on two clocks, when it happened and when it was recorded · 3 where accounts differ · 3 questions for the next appointment

    PrototypeView screenshot ↗
Demos are running now. We’re happy to start from your material: bring a few of your team’s standing conclusions, memos, determinations, filed analyses, and we’ll show you how they are managed in Exeges. Get in touch to set one up.

Get in touch